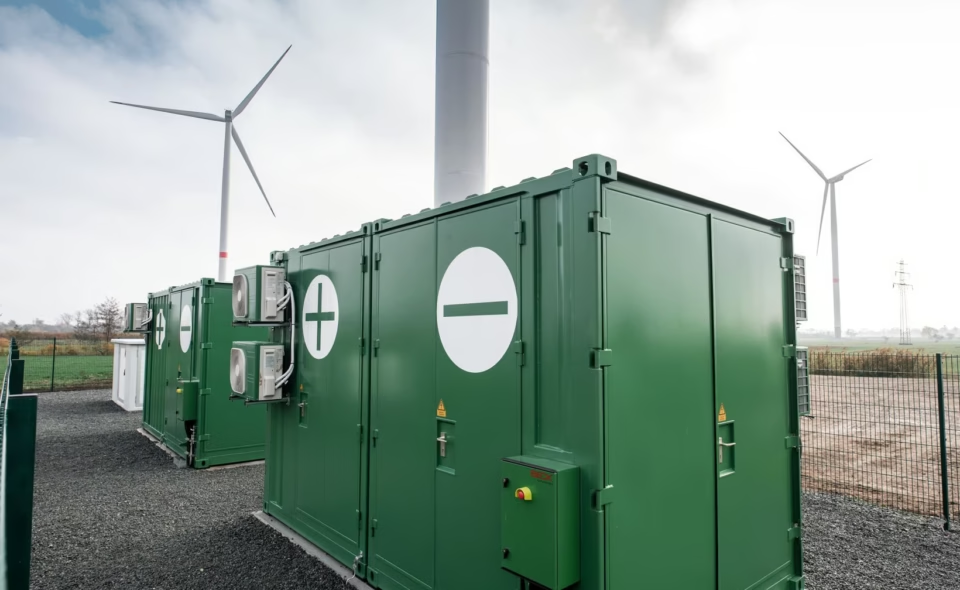
Europe’s energy transition is still being financed by a patchwork of public banks, institutional investors, corporate offtakers and project-level lenders — but the mix has shifted meaningfully since 2025. The dominant story of the second half of 2026 is no longer “abundant capital chasing scarce projects.” It’s abundant capital chasing bankable revenue, at a moment when solar’s own success — record build-out — is cannibalising the prices that early projects were financed against. Standalone and co-located battery storage has become the mechanism lenders now expect to see before they’ll underwrite new solar at scale, and the numbers back that up: Modo Energy tracked 82 European BESS financing deals in 2025 (more than triple 2024’s count), with disclosed debt jumping from €1.4 billion to €6.1 billion, and Q1 2026 alone added a further 53 deals and 11 GW of capacity — up 50% quarter-on-quarter. Layered on top is a genuine energy-security narrative: the IEA’s World Energy Investment 2026 report puts global energy investment at roughly USD 3.4 trillion for the year, with clean energy — renewables, grids, storage, nuclear and efficiency — accounting for close to USD 2.2 trillion, almost double fossil fuels, and solar PV alone drawing more capital than any other single technology. Below, we walk through the financing toolkit as it stands in H2 2026, compare how the major European markets are structuring deals, and look at where the pipeline is heading through 2027.
The financing toolkit — what’s changed since 2025
Project finance and bank debt remain the backbone of utility-scale solar and BESS, but the collateral lenders demand has hardened. Multilateral and national promotional banks — the EIB above all — are more central than ever: the EIB Group approved roughly €10 billion in new financing in April 2026 alone, with close to €2 billion earmarked for clean energy, and InvestEU-backed green loans have become the default underpinning for large solar and hybrid portfolios (Italy’s €507 million Project Sophocles with Natixis CIB and Sunprime; a €100 million loan to Ireland’s Power Capital for the 395 MWp Dolmen solar portfolio; a €50 million green loan to Matrix Renewables for 240 MW in Spain). Corporate PPAs still underwrite large PV volumes, but the balance has tipped further toward merchant and quasi-merchant structures as capture prices fall — which means the underwriters increasingly are asset managers, trading houses and optimisers rather than traditional utilities.
The single biggest shift in the toolkit is the rise of tolling and offtake agreements as a precondition for debt, not just an enhancement to it. In Germany, seven of nine disclosed 2025 BESS offtake deals fixed 70–100% of capacity for five to ten years, and that structure is now unlocking gearing of up to 85% — a level that would have been unthinkable for pure-merchant storage two years ago. Standalone tolling agreements in Europe rose from 3 in 2024 to 15 in 2025, and a further four project-finance deals in 2025 involved tolling counterparties. Asset rotation continues to recycle capital just as it did in 2025, but it’s increasingly paired with corporate divestment of storage stakes to insurers and pension funds at scale — the clearest example being TotalEnergies’ March 2026 sale of a 50% stake in 11 German battery projects (789 MW / 1,628 MWh) to Allianz Global Investors, a €500 million transaction that is 70% debt-financed. Structured, storage-specific revenue-stack financing — blending capacity payments, ancillary services and merchant arbitrage — is now the norm rather than the exception lenders are still learning to model.
Country-by-country snapshot — how local markets are diverging
United Kingdom. The UK’s BESS market delivered Europe’s largest project-finance close of the cycle — the 1.4 GW Thorpe Marsh deal — and Copenhagen Infrastructure Partners’ 500 MW Coalburn 1 has now reached commercial operation, completing AXA IM Alts’ entry into UK storage via its 50% stake purchase. CIP has since taken FID on the two sister projects, Coalburn 2 and Devilla (also 500 MW each), with construction due to start in 2027; together the three sites will deliver 1.5 GW / 3 GWh under a ten-year SSE Energy Markets optimisation agreement and a 15-year capacity market contract for Coalburn 1. The pattern — institutional joint ventures, 8–15 year project-finance tenors, and long-dated optimisation contracts — remains intact, but Germany has now overtaken the UK on deal count.
Germany. Germany led Europe on BESS financing deal count in both the full-year 2025 tracker (25 deals) and Q1 2026 (13 deals — more than double the UK’s six), and installed battery capacity reached 17.9 GW / 27.2 GWh by April 2026, with utility-scale additions overtaking residential for the first time on a quarterly basis. But 2026 is also a regulatory inflection point: roughly 720 GW of storage capacity sits in grid-connection queues against only 78 GW of confirmed connection commitments, prompting a new “maturity” framework whose first transmission-connected round closes at the end of June 2026 (results expected around December). A parallel change to §35 of the Federal Building Code now gives BESS above 1 MWh privileged planning status in rural areas, easing a permitting bottleneck that had made siting near substations difficult. Grid-fee exemptions are being redrawn too, with grandfathering tied to reaching FID before 4 August 2029 — meaning developers now have a hard financing deadline baked into their models. Against that backdrop, the TotalEnergies/AllianzGI stake sale and continuing tolling-backed project financings illustrate how institutional capital is adapting to a market that rewards speed and documentation over first-mover advantage alone.
Spain and Portugal. Iberia is where cannibalisation has moved from a talking point to a balance-sheet problem. Spain recorded 397 hours of negative day-ahead prices in Q1 2026 alone, against just 48 in the same period of 2025, and solar capture rates have fallen from roughly 83% in spring 2023 to around 54% in spring 2026. That has pushed the market decisively toward co-location: asset managers now openly favour hybrid solar-plus-storage over standalone PV in Spain given grid congestion and negative pricing, and new “zero-capex” models (such as Lunas Energy’s turnkey BESS offer to existing PV plant owners) let generators add storage without fresh equity. Distressed M&A activity is starting to appear in Spain as older PPA-backed assets, negotiated before the cannibalisation era, come under pressure. Portugal, meanwhile, saw one of the first commercial bank-backed structured hybrid financings in the country close in early 2026, covering Sonnedix’s Acail (28 MW solar / 24 MW BESS) and Felgueiras (40 MW solar / 32 MW BESS) projects, with solar due online in Q2 2026 and BESS following in Q3. Sonnedix followed that in August 2026 with a €730 million refinancing and construction facility covering 540 MW of solar and two BESS projects across France, Italy, Portugal and Spain — a sign that lenders are now comfortable underwriting multi-country hybrid portfolios in a single package.
France. France is undergoing its own version of the cannibalisation story: the share of French solar output produced during negative-price hours jumped from 29.2% in April 2025 to 45.1% in April 2026, and regulator CRE has proposed reforming large-scale solar CfDs to reference a baseload price index rather than a solar-capture price, while reducing compensation during negative-price periods — a change that will materially affect how new French solar is financed and hedged going into 2027. On the corporate side, French players are increasingly financing storage outside their home market: TotalEnergies’ German BESS divestment to Allianz is one example of French capital rotating toward markets with clearer revenue frameworks, even as EDF continues to anchor domestic solar and grid-upgrade financing.
Italy. Italy has become one of Europe’s most active BESS financing markets — third by deal count in 2025 with 12 transactions — helped by the long-awaited conclusion of the MACSE capacity auction, which allocated 10 GWh of BESS long-term revenue contracts and unlocked a wave of FIDs that had been on hold. The EIB’s €507 million Project Sophocles, signed with Natixis CIB and Sunprime in March 2026, will fund roughly 290 MWp of solar and 350 MW of BESS between 2026 and 2028, including in EU cohesion regions, with the EIB itself providing up to €271 million. Sonnedix’s August 2026 refinancing also weighted Italy most heavily, with over 350 MW of the 540 MW portfolio located there.
Netherlands, Nordics and Benelux. Institutional appetite and route-to-market sophistication remain strongest here. Belgium’s capacity remuneration mechanism continues to underwrite new storage — Engie and NHOA’s 320 MWh Drogenbos BESS secured a 15-year CRM contract from November 2027, with construction starting in March 2026. Nordic and Benelux portfolios continue to see corporate and institutional exits as a routine capital-recycling tool.
Central and Eastern Europe. CEE is where the map has changed most since 2025. Poland’s capacity market — four auctions between 2022 and 2025 — has contracted roughly 5.1 GW of deliverable BESS capacity (about 11 GW of physical battery capacity after de-rating), and Modo Energy now tracks 89 Polish utility-scale BESS projects totalling 12.5 GW, with developer R.Power leading at 1.7 GW. R.Power closed a PLN 270 million (€64 million) project-finance package with Siemens Financial Services and Erste Group for its 150 MW / 300 MW Jedwabno project in June 2026 — reportedly the largest utility-scale BESS project financing in Poland to date — while Northland Power acquired two further Polish projects (Mieczysławów and Kamionka, 300 MW combined) for an estimated €200 million. A new law, UC84, changes the cost structure for the entire Polish pipeline once its provisions take effect around October 2026. Hungary and Serbia entered Modo Energy’s European deal tracker for the first time in Q1 2026; Hungary’s debut deal was a ten-year CfD won at public auction and backed by €58.9 million of debt from UniCredit Hungary — a CfD-plus-commercial-debt template that other first-mover CEE markets are now watching closely. Hungary’s own first dedicated storage auction, targeting around 900 MWh, is due by the end of 2026, and Greenvolt has already brought the country’s largest BESS online (99.8 MW / 288.6 MWh at Buj), financed in January 2026 under a ten-year cap-and-floor subsidy scheme. Elsewhere in the region, the EBRD’s €70 million package to merchant storage operator NGEN, spanning projects in Latvia, Poland, Romania and Slovenia, shows public development banks still doing the risk-absorbing work — including first-loss guarantees — that private lenders won’t yet do alone in these markets.
Investment modes & risk allocation — the H2 2026 pattern
Public-bank co-financing remains decisive for anything with permitting, grid or merchant-revenue risk: EIB and EBRD guarantees, InvestEU frameworks and first-loss structures continue to be what converts a project from speculative to bankable in Italy, Ireland, Poland, the Baltics and the Balkans alike. Asset rotation is now standard practice rather than an opportunistic move — TotalEnergies/AllianzGI in Germany and Northland Power’s Polish acquisitions are 2026 examples of developers recycling capital out of construction-stage or newly operational assets into further build-out. What’s new is the extent to which tolling and offtake contracts have become a financing precondition rather than a bonus — a direct response to collapsing solar capture prices in Spain, France and increasingly Italy. Lenders are also stress-testing merchant exposure far more conservatively than in 2025, and revenue diversification — mixing capacity payments, tolling, ancillary services and arbitrage — is now close to mandatory for any debt-financed standalone BESS. Distressed situations are starting to surface, particularly in Spain, where assets financed against pre-cannibalisation PPA assumptions are being restructured or sold.
Why H2 2026 is different from 2025 — and what it means going into 2027
Two things distinguish this period from 2025. First, the cannibalisation problem has stopped being a forward risk that lenders modelled conservatively and become a live, quarter-by-quarter reality showing up in negative-price hour counts across Spain, France and Italy — which is why storage co-location has gone from “preferred” to “essential” for new solar financing in the most saturated markets. Second, several major regulatory resets are landing at once: Germany’s grid-connection maturity framework and building-code changes, France’s proposed CfD reform, and Poland’s UC84 law all reach decision points in the second half of 2026, and each will reshape the economics of projects reaching FID through 2027. Public banks are filling the gap this creates — the EIB’s ceiling increases and continued InvestEU deployment, and the EBRD’s first-loss guarantees in CEE, are both explicit attempts to keep private capital flowing into markets where regulatory or grid risk would otherwise price it out.
Notable H2 2026 deals to know
TotalEnergies sold a 50% stake in 11 German battery projects (789 MW / 1,628 MWh) to Allianz Global Investors for €500 million, 70% debt-financed, with completion due by 2028 — the clearest signal yet of insurer appetite for German storage at scale. CIP’s Coalburn 1 in Scotland reached commercial operation, completing AXA IM Alts’ UK storage debut, while CIP took FID on the 1 GW Coalburn 2/Devilla follow-on projects for 2027 construction. In Italy, the EIB, Natixis CIB and Sunprime signed the €507 million Project Sophocles financing, and Sonnedix closed a €730 million refinancing spanning four Southern European countries. In Poland, R.Power secured a record PLN 270 million project financing for its Jedwabno BESS, and Northland Power acquired two further Polish storage projects. Hungary recorded its first-ever tracked BESS financing deal — a CfD-plus-bank-debt structure from UniCredit Hungary — while Greenvolt brought the country’s largest operating BESS online at Buj.
Practical advice for stakeholders
Developers in Spain, France and increasingly Italy should treat storage co-location as a financing requirement, not an optional upside — and should watch regulatory deadlines (Germany’s FID cut-off, Poland’s UC84 provisions, France’s possible CfD reform) as hard dates that affect bankability, not background policy noise. Institutional investors should prioritise assets with tolling or capacity-market contracts covering the bulk of near-term revenue, given how much conservative underwriting has tightened around merchant exposure, while watching Spain specifically for distressed-asset opportunities. Banks and lenders should keep leaning on EIB and EBRD guarantees to extend tenor in markets with grid or regulatory uncertainty, and should expect tolling coverage — not just PPA coverage — to become a standard covenant for BESS debt. Policymakers, especially in Germany, France, Spain and Poland, face a shared task: without faster grid reinforcement and clearer long-term revenue-stabilisation mechanisms, negative pricing and curtailment will keep eating into the bankability of new solar, regardless of how much capital is theoretically available.
Where capital is heading through 2027
Storage has finished its transition from “nice to have” to structurally necessary in Europe’s most saturated solar markets, and the deal flow of H2 2026 confirms it: co-located and standalone BESS financing is growing faster than solar-only financing almost everywhere except the least-penetrated CEE markets. Public banks and guarantee mechanisms will keep doing the work of converting speculative projects into bankable ones, particularly as Germany’s connection-queue reforms, France’s possible CfD overhaul and Poland’s new cost structure all bite through 2026 and into 2027. Watch Spain and France closely for early signs of distressed refinancing as older PPA-era assets meet today’s capture prices, and watch Hungary, Serbia and the wider Balkans for the CfD-plus-commercial-debt template — first proven in Q1 2026 — to spread as more first-mover CEE markets look to replicate Poland’s capacity-market playbook. The direction of travel for 2027 is clear: revenue certainty, not just capital availability, will decide which projects get built.
Join Power & Money in Amsterdam for a day filled with energy finance panels and networking with top investors, sponsors of energy projects: