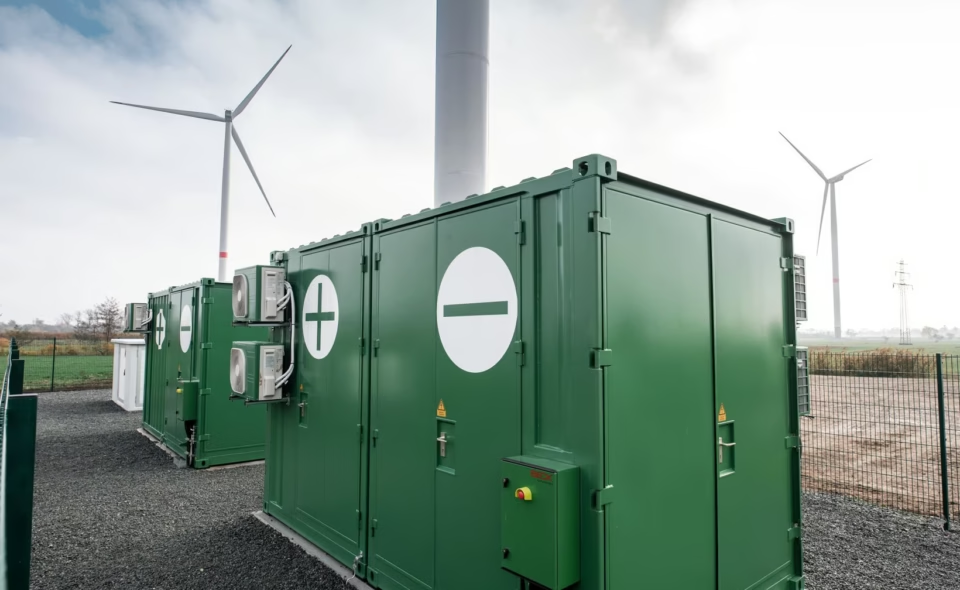
JLL advised Navacant, a Spanish renewable energy and storage developer, on the sale of a 126 MW battery storage portfolio in Valencia to BW ESS, the global storage platform owned by BW Group. The portfolio, named Project Sorolla, comprises two standalone battery projects with 99 MW and 27 MW of grid connection capacity and up to 675 MWh of combined storage. After roughly 18 months of development, the projects are targeting Ready-to-Build (RTB) status in 2027 and commercial operation in 2028. CST Energy, a Navacant development partner, will continue managing the projects through the remaining pre-construction phase; BW ESS takes over from there.
The deal is an example of a broader pattern in European battery storage M&A: buyers increasingly acquire projects before construction starts, rather than waiting for operational assets. According to deal-tracking data published by Enerdatics, projects that reach Ready-to-Build status in Europe currently sell for between $50,000 and $170,000 per megawatt, compared with roughly $20,000 per megawatt for early-stage projects still working through permitting. European battery storage M&A activity rose 120% year-on-year in the third quarter of 2025, across 22 deals covering 18 GW of capacity, per the same data.
Other recent deals follow similar structures. Prime Energy’s 2026 acquisition of a 79-project, 29 GWh Spanish storage platform involved an initial payment of €5–10 million, rising to as much as €350 million as projects reach development milestones; the platform’s valuation was set to roughly double, from €45 million to €90 million, if 2 GW of its projects reach RTB by 2027–2028. In Italy, Sosteneo, an infrastructure fund managed by Generali, paid €1.1 billion in 2024 for a 49% stake in Enel’s Libra Flexsys battery storage platform, covering roughly 1.7 GW of operational and pipeline projects. In the UK, Macquarie Asset Management increased its existing stake in solar and storage developer Island Green Power in 2025, adding exposure to the developer’s broader project pipeline rather than a single asset.
Tomás García, JLL’s head of Energy & Infrastructure Advisory for Iberia, said the transaction reflects institutional investors treating standalone battery storage “as a distinct asset class with compelling risk-adjusted returns.” César Izco, a partner at Navacant, said the sale “validates” its development approach. BW ESS executive director Isaac García Moreno said the company is pursuing growth in Spain “through a combination of greenfield development and acquisitions of high-quality projects at an advanced stage.”
BW ESS entered the Spanish market in 2025 through a separate 50/50 joint venture with developer Ibersun, targeting 2.2 GW of greenfield battery storage across eight projects. The Navacant acquisition adds to that position through a different route — buying an advanced-stage portfolio rather than developing one from scratch.