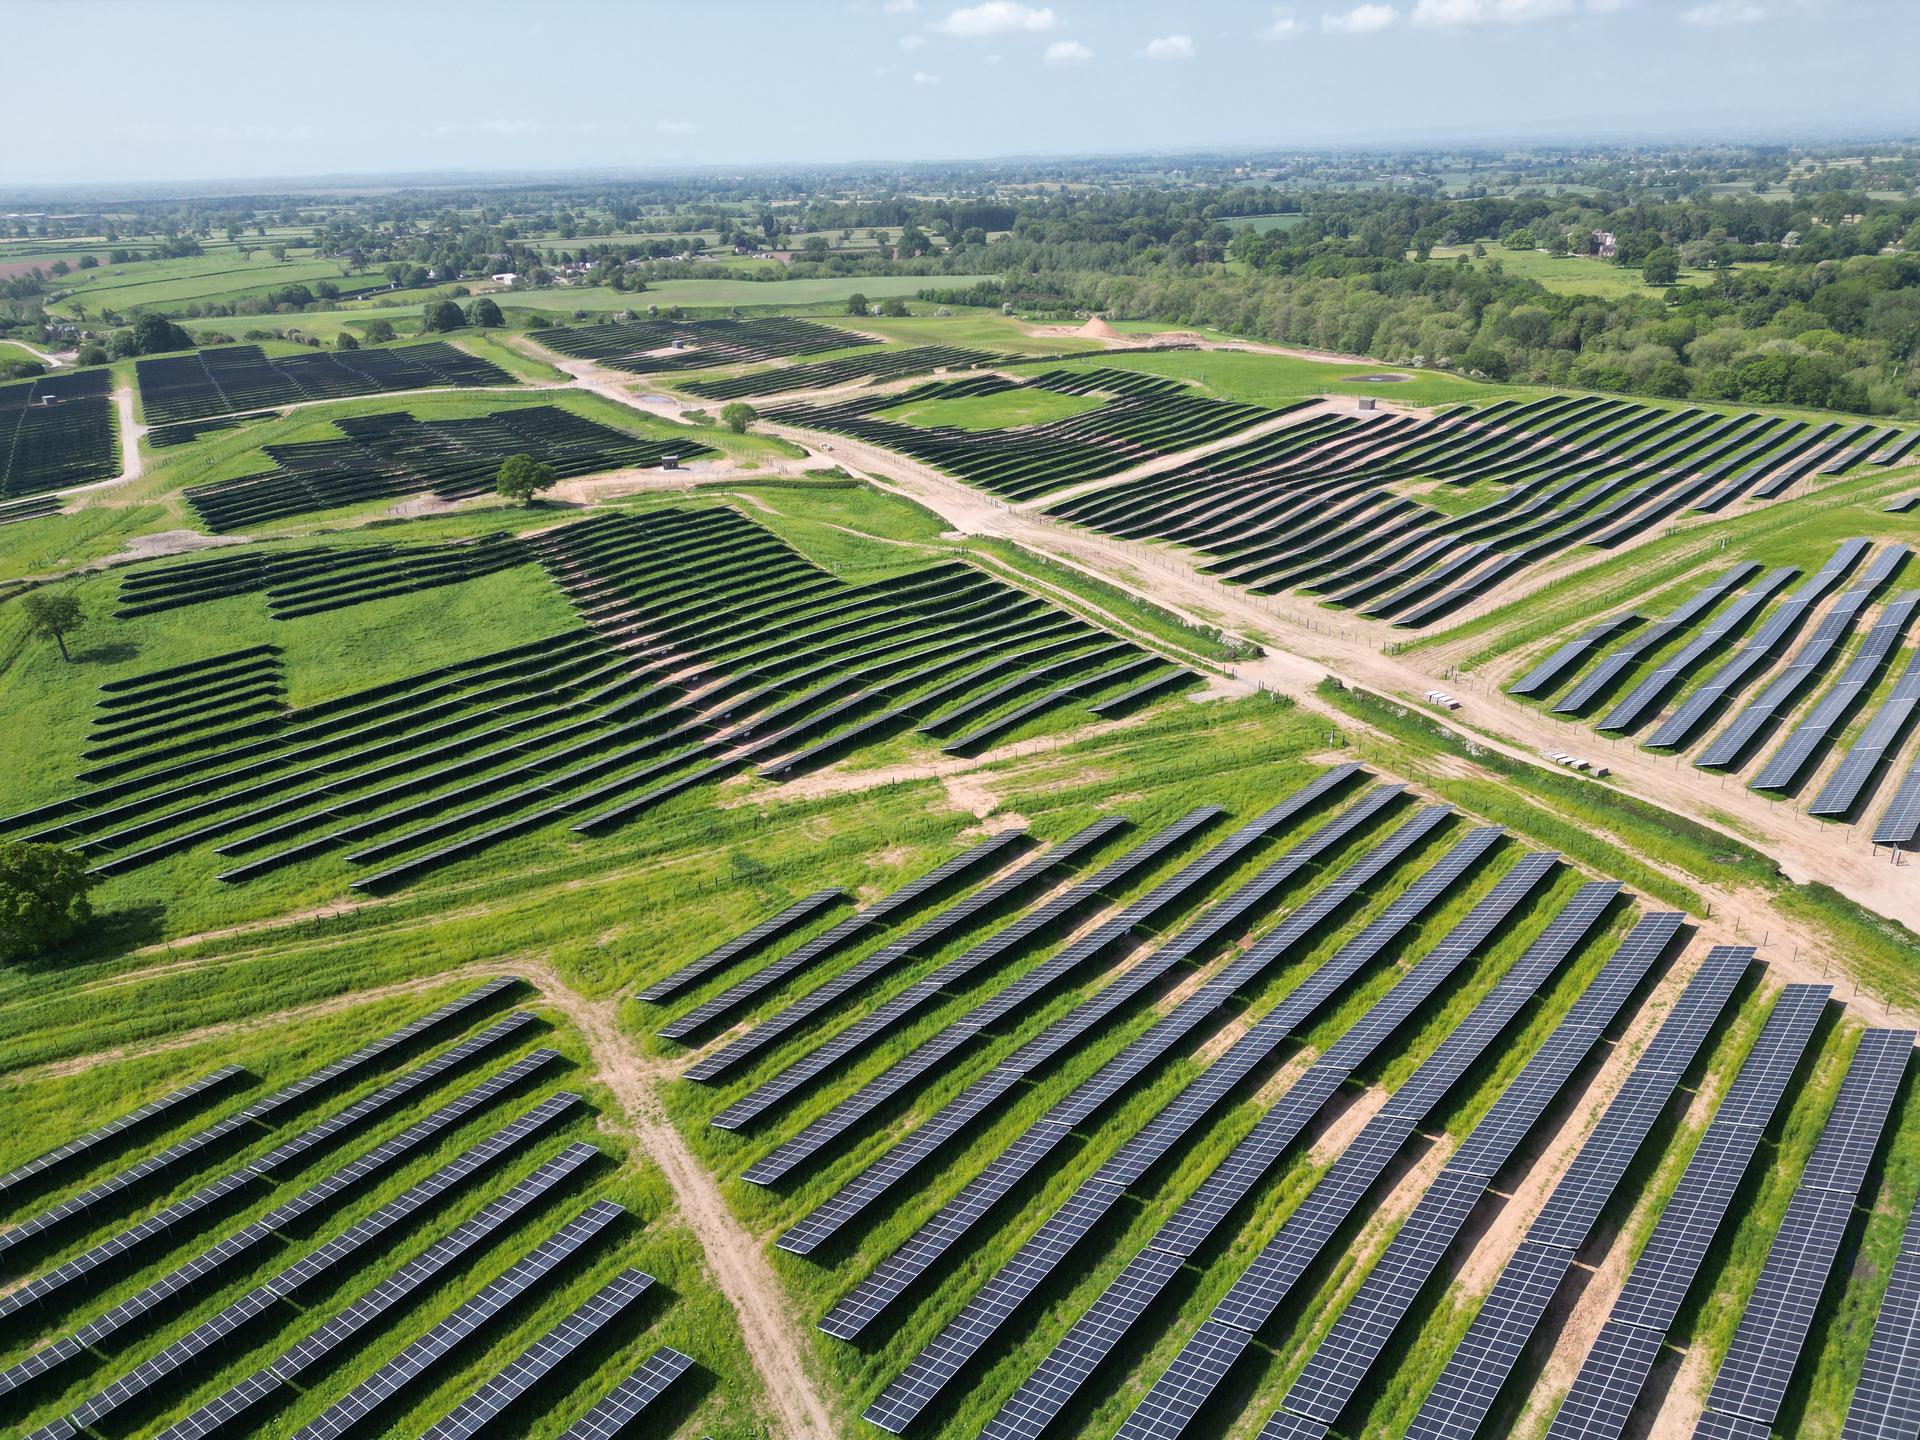
Ukraine’s Solar Energy Association (SEAU) expects the country to add at least 1.5 GWs of new solar capacity and more than 3 gigawatt-hours of new battery storage in 2026 — a forecast that, if it holds, would essentially repeat 2025’s performance rather than exceed it. That framing matters, because most of the coverage this figure has generated treats it as a fresh government target. It isn’t. It’s an industry association’s read on where the market is already headed, built on a year in which Ukraine added 1.5 GW of solar (nearly double 2024’s 800 MW) and roughly 2.9 GWh of battery storage — a fivefold jump that pushed the country into fifth place among European storage markets, behind only Germany, the UK and Italy.
The more consequential development sits underneath that headline number, in a piece of auction design most international coverage has skipped past: for the first time, Ukraine’s government has carved out a dedicated support category specifically for solar paired with storage, separate from standalone solar and wind. It is a small category — 100 MW out of a 1 GW national quota for 2026 — set against a market SEAU expects to move by 1.5 GW and 3 GWh. Understanding why a 100 MW policy lever is supposed to help steer a market more than ten times its size is the actual story here.
How the quota got to where it is
The starting point was smaller still. Cabinet of Ministers Resolution No. 298-r, dated April 1, 2026, set Ukraine’s initial 2026 green-auction quotas at just 330 MW combined: 33 MW of solar east of the Dnipro River, 250 MW of wind nationwide, and 47 MW split across biomass, biogas and small hydropower. Less than two months later, on May 27, 2026, the government amended that resolution and nearly tripled the total to 1 GW. The revised breakdown, announced by First Deputy Prime Minister Denys Shmyhal, allocated 700 MW to wind, 150 MW to biogas/biomass/small hydro, 50 MW to standalone solar — and, as a new line item, 100 MW specifically for solar-plus-storage. Shmyhal framed the increase as a way to “encourage the construction of new generation capacity and attract additional private investment into the renewable energy sector,” according to the Ministry of Energy of Ukraine.
The solar-plus-storage category isn’t just a capacity number; it comes with its own rulebook, established under Law No. 4777-IX and reported in detail by Energy-Storage.News. Projects in this category must pair at least 80% of the solar plant’s generation capacity with storage, and the storage must total a minimum of 2 kWh for every 1 kW of installed PV. The category carries a support price cap of €0.12/kWh — half again higher than the €0.08/kWh cap for standalone solar and wind — and by law it must receive at least 10% of the annual national auction quota, double the 5% floor set for solar and wind individually. Support contracts under the category run through 2034, well beyond the typical planning horizon Ukrainian developers have worked with since the war began. Vladyslav Sokolovskyi, chairman of SEAU, described the effect on developers plainly: “the market is gaining more predictability, a longer planning horizon, and a lower entry threshold,” adding that prioritizing solar-plus-storage means “such assets are more likely to offer a more stable revenue model going forward.”
The first live test of the new category arrives in September 2026. State enterprise Guaranteed Buyer has scheduled three auctions: 700 MW of wind on September 30 at the 8 euro-cent cap, and, on September 25, the 100 MW solar-plus-storage tranche at 12 euro cents alongside a separate 50 MW standalone-solar tranche at 8 euro cents. Projects are eligible across Kyiv and 13 other regions, with active combat zones and occupied territory excluded. The Ukrainian Wind Energy Association welcomed the broader package as addressing “Ukraine’s power system needs today for safe and reliable operation amid modern challenges.”
Why a 100 MW quota is supposed to move a 1.5 GW market
Here is the part that tends to get flattened in coverage that just repeats “Ukraine targets 1.5 GW solar, 3 GWh storage”: the subsidized auction quota and SEAU’s market-wide forecast are not the same number, and they’re not meant to be. The 100 MW solar-plus-storage category is a fraction — roughly one-fifteenth — of the capacity SEAU expects the broader market to add in solar alone next year, and a still smaller fraction of the storage figure. Most of Ukraine’s recent solar and storage growth has come from outside the state-auction system entirely: commercial and industrial projects buying batteries directly, net-billing prosumers (Ukraine has more than doubled its prosumer count year-on-year, past 100,000 households), and corporate investment such as the agricultural conglomerate Kernel’s planned $400 million build-out of up to 600 MW of combined wind, solar and storage by 2028, including what would become the largest solar park in western Ukraine, a 250 MW project in Chernivtsi region.
Given that backdrop, the auction category’s job isn’t to supply the volume — it’s to de-risk the asset class for the capital that’s already flowing toward it outside the subsidy system. A guaranteed 12-cent floor price, a mandated storage ratio, and a support contract running to 2034 give banks and private investors a bankable reference point for a technology combination — solar paired one-for-one-plus with batteries — that didn’t have a dedicated Ukrainian support mechanism before this year. Whether 100 MW of subsidized precedent is enough to keep the other roughly 1.4 GW of solar and 3 GWh of storage moving at market rates through a fourth year of full-scale war is precisely what SEAU’s forecast is betting on, and what the September auction results will start to indicate.
The resilience logic behind the numbers
None of this is happening in a vacuum separate from the war. Ukraine’s cumulative solar capacity has passed 8.5 GW, according to pv magazine’s reporting on SEAU data, built back up after the country lost an estimated 2.6 GW of solar capacity to occupation and shelling, mostly in 2022. Ekonomichna Pravda’s tally of annual additions — roughly 0.5 GW in 2023, 0.8–0.85 GW in 2024, 1.5 GW in 2025, and a projected 1.5 GW in 2026 — puts total new solar generation added since 2023 at more than 4 GW, which the outlet notes already exceeds what the country lost from 2022 onward. Wind has recovered far more slowly, having lost roughly 80% of its pre-war generation to occupation or damage: additions were 146 MW in 2023, just 20 MW in 2024, 324 MW in 2025, and a forecast 500–600 MW in 2026.
Storage carries an explicit military logic in Ukrainian industry commentary that doesn’t map onto how the technology gets discussed in Western Europe. “Batteries are more than an energy technology; they are a resilience technology,” Sokolovskyi told pv magazine in August 2026. “In Ukraine, it is bought to keep the lights on” — a contrast, he noted, with Western European households that buy batteries mainly to store rooftop solar or shave electricity bills. That resilience framing predates this year’s auction redesign: grid operator Ukrenergo’s 2024 ancillary-services auctions already resulted in 398 MW of storage capacity being commissioned during 2025 specifically for grid balancing and frequency response, and Ukraine’s largest battery project to date — a 200 MW/400 MWh system associated with utility DTEK — came online in September 2025. Distributed storage, serving homes, small businesses and critical infrastructure, accounted for more than 60% of 2025’s new capacity, with utility-scale projects making up roughly a third of the remainder.
What comes after 2026
Even a repeat of 2025’s 1.5 GW/3 GWh performance in 2026 would leave Ukraine well short of the trajectory its own officials have described for the rest of the decade. Serhii Nahorniak, an MP who chairs the parliamentary Subcommittee on Energy Saving and Energy Efficiency, has cited 2030 goals of 3.6 GW of wind, 10 GW of solar, and 1.5 GW of storage power capacity delivering 4 GWh total (on a four-hour discharge basis) — against a current base of roughly 0.4 GW of operating battery storage. He has described the buildout in blunt terms, calling investment in renewables and storage “a matter of the power system’s survival under wartime conditions,” while also pointing to the parallel benefit of preparing Ukraine’s grid for synchronization with the European ENTSO-E network. Separately, market-research firm HOMEDOME estimates that distributed solar alone may need to reach roughly 12.2 GW by 2030 to meet demand — implying the current annual pace would need to run two-and-a-half to three times faster than it is now.
Set against those numbers, the 2026 auction redesign reads less like a finish line and more like Ukraine testing whether a narrow, well-structured subsidy category can pull private capital toward exactly the asset combination — solar plus storage — its officials say the power system needs most, without the state having to fund the buildout itself. The 100 MW allocated to that category this September is a small bet by the standard of the 1.5 GW and 3 GWh SEAU expects the wider market to deliver regardless. Whether that bet pays off in bankability rather than raw megawatts is a question the current data can’t yet answer — it’s one for the 2027 quota-setting process, when the government decides whether to expand the category or leave it as a pilot.